
WEEK ENDING 10/16/2026
-
- CPI and PPI releases are hotter than expected
- AI trade is showing some cracks
- Add it all up, and it equals “Flight to Quality”
- Some decisions get reversed
A CITY DIFFERENT TAKE
In a holiday-shortened week, we expected a quiet week for the market; we were wrong! CPI was released on October 14, 2026. It came in hotter than expected. Core Y/Y was 2.6% verses expectations of 2.5% and last month’s 2.4%. The PPI release followed on 10/15 and came in hotter than expected, at 5.00% versus expectations of 4.4% and last month’s upward revision to 4.8%. Given these facts, one would have expected an increase in rates across the board. The following table highlights several index changes for the week ending October 16, and gives some hints as to why the opposite happened:
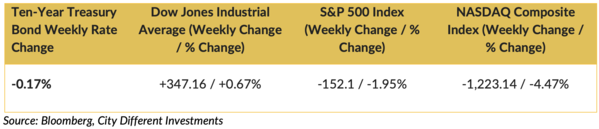
One can see that equity indexes with higher exposure to AI participants took the biggest hits, and Treasury yields moved lower despite higher inflation indicators, as investors sought safety.
“This past week, investors questioned some of the core ideas undergirding the artificial-intelligence trade, and the market action got ugly.” Ouch
This is the setup for a classic flight-to-quality rally.
THE TREASURY MARKET
The following table highlights the change in yield for several representative Treasury tenors.
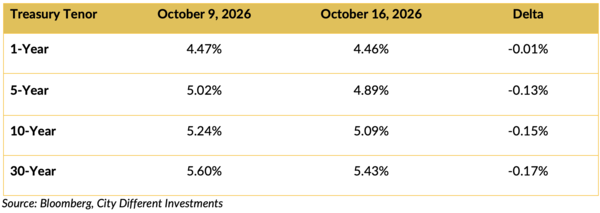
The slope of the Treasury yield curve as measured by the spread between 2- and 10-year maturities flattened for the week ending at 0.35%, versus last week’s close of 0.44%. Taxable bond funds saw $10.7 (B) of outflows for the period ending 9/30/2026 before turning around with $4.6 (B) in inflows for the period ending 10/7/2026.
Quality spreads were largely unchanged. The spread between the Bloomberg US AAA total return index (5.17%) and the Bloomberg UA Baa total return index (6.10%) was 0.93% at week’s end. This reading is still narrow by CDI’s calculations, with a standard deviation of -0.73. The spread using the Bloomberg US Corporate High Yield Index (8.38%) was +3.21%. This reading is still narrow by CDI’s calculations, with a standard deviation of -0.57.
THE MUNICIPAL MARKET
The municipal market outperformed the Treasury market over the last week. Treasury yields in 1.5, 10, and 30-year maturities were lower for the week. The yield change for those maturities was (-0.01%, -0.13%, -0.15%, and -0.17%). In the municipal market, the yield changes for those maturities were (-0.22%, -0.23%, -0.22%, and -0.17%). On a ratio basis relative to the Treasury market, AAA general obligation municipal bond yields are equal to or exceed the after-tax breakeven ratio, but are below their long-term averages as CDI calculates them.
Municipal bond funds saw investors pull $5.5 (B) out of them for the week ending 10/7/2026. In contrast, municipal bond ETFs saw positive cash flow for the same period of $5.0 (B). The 2-10 spread for AAA general obligation bonds narrowed a little to 0.63% from 0.64%. This spread is historically narrow based on the CDI calculation. It is currently -1.13 standard deviations below the long-term average. Quality spreads have not moved; the AAA-BBB spread in ten years is 0.85% versus last week’s -0.86%.
THE CORPORATE MARKET
Corporate bond yields moved lower on the week, outperforming their Treasury equivalents. Investment-grade corporate yields were lower between 0.01% and 0.15%, depending on maturity.
THIS WEEK IN WASHINGTON
Several decisions by the Administration have been reversed this week.
- There will be no live streaming of the Fort Hood shooters' execution.
- Kimberly Guilfoyle has resigned as Greek ambassador. This story is not over.
- Katie Zacharia is no longer the press secretary after five days. Anthony Scaramucci lasted in the role 10 days. So, can we measure this as ½ a “Mucc”?
CONCLUSION
Not many folks have seen flight-to-quality rallies like the one we saw last week. They can be big and fast. CDI prefers to focus on fundamentals when setting our policy exposures. Inflation is still a problem. We will continue to focus on fundamentals and our discipline.
CDI continues to believe that this rise in rates will continue and is a buying opportunity. Who doesn’t like buying stuff on sale? But as new risks emerge due to rising rates, investors must be aware of them.
IMPORTANT DISCLOSURES
The information and statistics contained in this report have been obtained from sources we believe to be reliable but cannot be guaranteed. Any projections, market outlooks or estimates presented herein are forward-looking statements and are based upon certain assumptions. Other events that were not taken into account may occur and may significantly affect the returns or performance of these investments. Any projections, outlooks or assumptions should not be construed to be indicative of the actual events which will occur. These projections, market outlooks or estimates are subject to change without notice.
Please remember that past performance may not be indicative of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product or any non-investment related content, made reference to directly or indirectly herein will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions.
All indexes are unmanaged, and you cannot invest directly in an index. Index returns do not include fees or expenses. Actual portfolio returns may vary due to the timing of portfolio inception and/or investor-imposed restrictions or guidelines. Actual investor portfolio returns would be reduced by any applicable investment advisory fees and other expenses incurred in the management of an advisory account.
You should not assume that any discussion or information contained herein serves as the receipt of, or as a substitute for, personalized investment advice from City Different Investments. To the extent that a reader has any questions regarding the applicability above to his/her individual situation or any specific issue discussed, he/she is encouraged to consult with the professional advisor of his/her choosing. City Different Investments is neither a law firm nor a certified public accounting firm and no portion of this content should be construed as legal or accounting advice.
A copy of City Different Investments' current written disclosure statement discussing our advisory services and fees is available for review upon request.
Unless otherwise noted, City Different Investments is the source of information presented herein.
A description of the indices mentioned herein is available upon request.